Top 6 Lenders for Personal Loans for High Income Individuals in 2026
Last updated: 2026-10-16
High earners often hit a wall when trying to access liquidity. You might see a massive salary on your tax returns, yet finding a lender that understands your complex cash flow or specific tax structures can feel like a marathon. It isn’t just about grabbing the cash. It is about finding a partner that respects your time and your financial sophistication.
For many top-tier professionals—surgeons, corporate executives, or specialized engineers—standard algorithmic lending models often miss the mark. These models fail to capture the nuances of your actual wealth. You might have significant deferred compensation, stock options, or seasonal bonuses that don’t show up on a traditional pay stub in a way that a basic credit model understands. This discrepancy can lead to frustrating denials or suboptimal interest rates despite an impeccable net worth.
Choosing the right lender requires looking beyond surface-level interest rates. You need to consider the speed of funding, the flexibility of repayment terms, and the ease of the digital interface. For those with significant assets, the friction of paperwork can be a dealbreaker. If you are closing a real estate deal or a private equity investment, spending three days uploading tax returns to a legacy bank is not an option.
This list focuses on providers that balance efficiency with the specific needs of high-net-worth borrowers. We prioritized those who offer digital-first experiences and rapid deployment of capital. We want to highlight lenders that won’t slow down your momentum when you need to move quickly on an opportunity.
- Discover
- Avant
- JetzLoan
- OneMain Financial
- LendingPoint
- Upgrade
How These Financial Providers Were Evaluated
The evaluation process focused on the specific requirements of high-income earners. This includes the ability to secure significant loan amounts without the cumbersome requirement of collateral. Many professionals need the ability to borrow against future earnings or current assets without a hard credit pull during the initial phase. We specifically looked for lenders that utilize “soft pulls” for the pre-qualification stage. This allows you to run the numbers without any risk to your credit score.
Speed of capital deployment was another critical metric. A high-earner might need funds for a sudden real estate opportunity or a strategic investment. Therefore, lenders that offer rapid funding, sometimes within twenty-four hours or even a single hour, were prioritized. We also looked at the transparency of their digital application processes to ensure no hidden surprises. A lender that hides “origination fees” deep within a 20-page PDF is a red flag for a borrower who values efficiency and clarity.
Furthermore, we examined the scalability of the loan products. A lender that only offers $5,000 might be useful for a minor repair, but it fails to serve the needs of someone looking to consolidate high-interest debt or fund a significant lifestyle upgrade. We sought out providers that offer a meaningful ceiling on loan amounts, typically $30,000 or higher. This ensures the liquidity provided is actually useful for high-net-worth strategic planning.
Comparative Overview of Top Lenders
| Lender Name | Max Loan Amount | Funding Speed | Interest Rate / APR Info | Credit Check Impact |
|---|---|---|---|---|
| Discover | $40,000 | Next business day | 6.99% – 24.99% | No impact for pre-approval |
| Avant | See site | See site | See site | See site |
| JetzLoan | $50,000 | As little as 24 hours | See site | No hard credit pull |
| OneMain Financial | $30,000 | As soon as 1 hour | Starting at 11.99% APR | No impact for checking |
| LendingPoint | $36,500 | See site | See site | No impact for checking |
| Upgrade | $50,000 | Fast funding | See site | No impact for checking |
Ranking the Best Lenders for High Earners
1. Discover
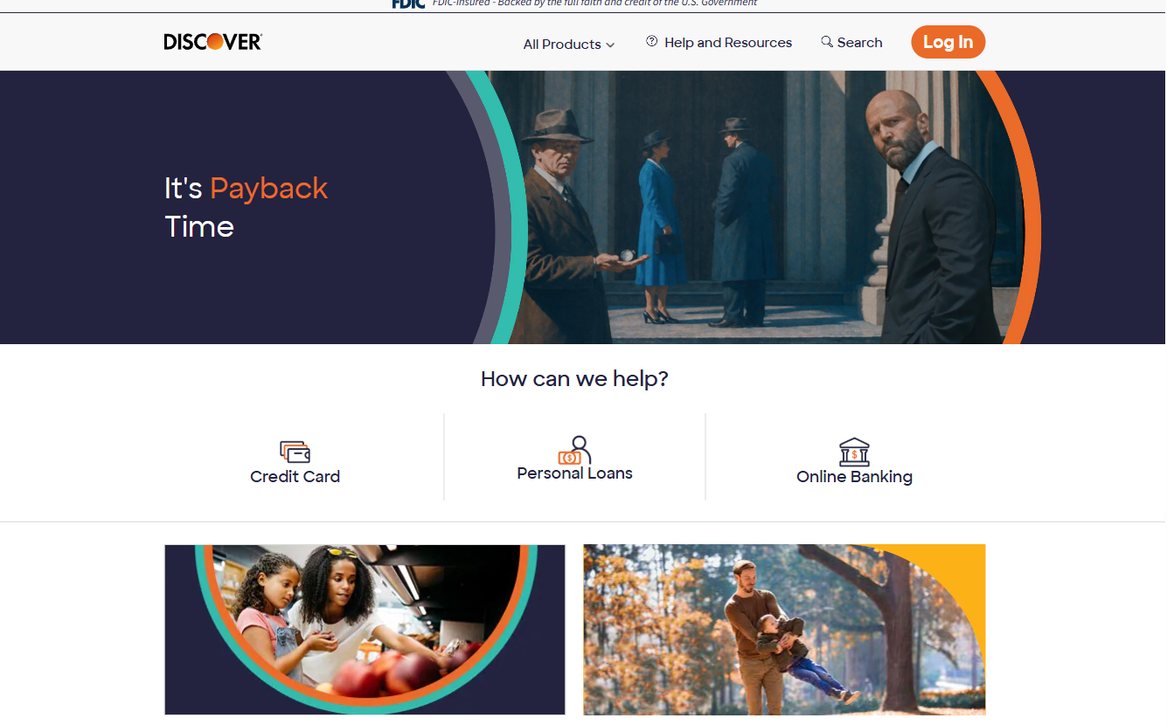
Discover is a solid choice for those who value a brand backed by the full faith and credit of the U.S. Government. Their personal loans are straightforward, offering amounts from $2,500 up to $40,000. It is a reliable choice for those who want stability and a well-established institution behind their debt. If you are tired of fintech startups that might pivot their business model overnight, Discover offers a sense of permanence and institutional security.
The platform is incredibly user-friendly, allowing for a quick check to see if you are pre-approved. This is vital for high-income individuals who do not want to see their credit score take a hit just to see what kind of terms they might qualify for. It is a low-friction way to explore your options. The digital interface is streamlined, minimizing the time spent navigating through unnecessary menus. This is a luxury in itself for the time-constrained professional.
Pros:
- Funds can be sent as early as the next business day.
- No fees and flexible terms are available.
- Pre-approval check does not impact your credit score.
Cons:
- Maximum loan amount is capped at $40,000.
2. Avant
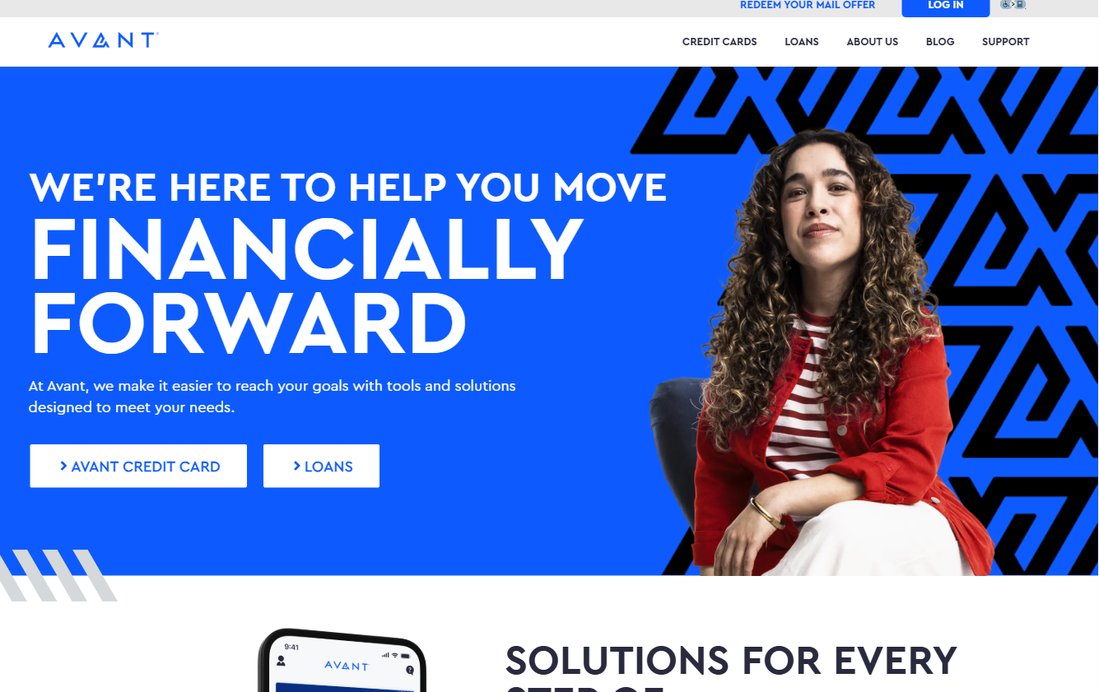
Avant focuses on providing tailored solutions for people who are actively moving their financial lives forward. They offer a variety of products, including credit cards and loans designed for debt consolidation or home improvements. It is a versatile option for those who need a lender that can adapt to different life stages. For example, your debt-to-income ratio might fluctuate during a transition from a high-earning associate to a partner in a firm.
The company emphasizes flexible choices and friendly support, making it easier to navigate the complexities of personal debt. Whether you are looking for a quick fix for an unexpected expense or a long-term strategy for debt management, their tools are built to simplify the journey. Their approach is less about “one size fits all” and more about providing a menu of options that align with your specific financial velocity.
Pros:
- Flexible loan solutions for various needs.
- User-friendly digital tools for managing finances.
- Provides multiple paths for debt management.
Cons:
- Specific loan terms and limits are not explicitly detailed.
3. JetzLoan
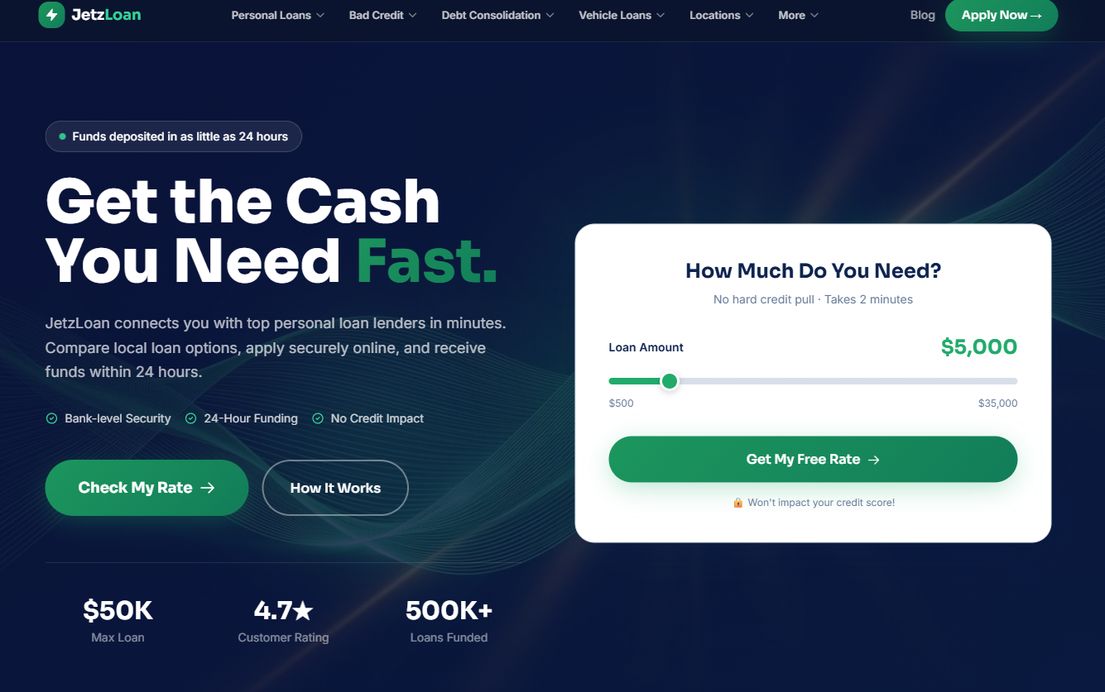
For the professional who needs capital yesterday, JetzLoan is a high-speed contender. They connect you with top lenders in minutes and can facilitate funding in as little as twenty-four hours. This is perfect for those who find the traditional banking pace to be far too sluggish for their lifestyle. If you have been presented with a time-sensitive investment opportunity—perhaps a real estate auction or a private placement—the speed offered here is a significant competitive advantage.
The process is incredibly streamlined, taking less than two minutes to complete a simple form. With a maximum loan amount of $50,000, they cater to significant needs without the headache of a hard credit pull during the initial rate check. This “marketplace” model allows you to see a broad spectrum of options without the repetitive task of applying to multiple banks individually. It saves you hours of administrative overhead.
Pros:
- Extremely fast funding, potentially within 24 hours.
- No hard credit pull required for initial rate check.
- High maximum loan amount of $50,000.
Cons:
- The platform acts as a connector rather than a direct lender.
4. OneMain Financial
OneMain Financial is a powerhouse for those who prefer a mix of digital ease and human interaction. They offer personal loans ranging from $1,500 to $30,000, with rates starting at 11.99% APR. Their ability to provide money as soon as one hour after signing is a massive selling point for urgent needs. This level of speed is rare in the unsecured loan market and makes them a top choice for emergency liquidity.
If you prefer talking to a real person, you can visit one of their 1,300 branches. This hybrid model is ideal for high earners who might want the convenience of an app but still value the security of a face-to-face meeting when dealing with significant financial matters. Having a physical location to visit can provide peace of mind, especially if you need to discuss complex repayment structures or specific documentation that a purely digital lender might reject.
Pros:
- Rapid funding, potentially in just one hour.
- Extensive branch network for in-person support.
- Flexible terms from 24 to 60 months.
Cons:
- Rates for unsecured loans can be higher than secured options.
5. LendingPoint
LendingPoint positions itself as a solution for various life events, from weddings to medical expenses. They offer loans between $1,000 and $36,500, providing a solid middle ground for those who need more than a small micro-loan but less than a massive mortgage. Their underwriting process is designed to be more sophisticated than basic consumer lenders, often looking at a broader picture of your financial health.
The platform is designed to make money easy, with a process that allows you to check your rate without impacting your credit score. This allows you to shop around and compare your options against other lenders without any financial penalty to your credit profile. This ability to “window shop” is critical for high-earners who are often managing multiple lines of credit and need to be precise about which debt they are taking on and at what cost.
Pros:
- Wide range of loan purposes supported.
- Check rates without impacting credit scores.
- Significant loan amounts up to $36,500.
Cons:
- Loan amounts are lower than some specialized lenders.
6. Upgrade
Upgrade is a comprehensive financial tool for the modern consumer, offering personal loans up to $50,000. They focus on speed and high-tech integration, allowing you to see rates in minutes. It is an excellent choice for those who want to manage their loans, savings, and checking in one ecosystem. Their technology-forward approach reduces the “friction of friction,” meaning fewer steps between application and disbursement.
Their ecosystem is quite robust, with options to earn cash back on various transactions and high APY on savings. It is a “one-stop-shop” approach that appeals to high earners who want to consolidate their financial life into a single, efficient digital interface. By centralizing these functions, you can get a clearer view of your total liquidity at any given moment, which is essential for sophisticated cash flow management.
Pros:
- Large loan limit of up to $50,000.
- Integrated financial ecosystem with savings and checking.
- Fast rate checking with no credit impact.
Cons:
- The complexity of the ecosystem might feel overwhelming to some.
Strategic Use of Personal Loans for High Earners
For those with high income, personal loans should not just be viewed as “debt,” but as a strategic tool for capital management. When used correctly, these loans can serve as a bridge to larger wealth-building opportunities. Consider the following strategic applications:
Arbitrage Opportunities: If you encounter a time-sensitive investment—such as a distressed real estate sale or a private equity opportunity—a personal loan can provide the necessary liquidity to secure the deal while you wait for your quarterly bonus or the sale of another asset to close. The cost of the interest is weighed against the potential upside of the investment.
Tax Optimization: While personal loans are not tax-deductible in the same way mortgage interest is, they can be used to manage cash flow during high-tax years. For example, using a loan to fund a major capital expense now might allow you to defer using your own cash reserves, keeping your liquidity available for other high-yield investments.
Debt Refinancing: High earners often carry multiple lines of credit, including premium credit cards with varying interest rates. Consolidating these into a single, lower-interest personal loan can simplify your monthly cash flow and reduce the total interest paid over time.
Avoiding Pitfalls in Personal Lending
Even with a high income, it is easy to make mistakes that can erode your wealth over time. One of the most common errors is ignoring the total cost of credit in favor of a low monthly payment. When you are looking at a $50,000 loan, a difference of 2% in interest can result in thousands of dollars of wasted capital over the life of the loan. Always look at the APR, not just the monthly installment, to see the true cost of your borrowing. The APR accounts for both the interest rate and any mandatory fees, giving you the most accurate picture of the cost.
Another mistake is failing to compare the funding speed with the necessity of the funds. If you need money for an immediate opportunity, a slightly higher rate might be worth it if the capital arrives in an hour. For example, if a business opportunity requires a 24-hour turnaround, a 12% loan delivered in an hour is far more valuable than a 7% loan that takes ten days to process. Conversely, for long-term debt consolidation, prioritize the lowest possible APR over speed.
Lastly, keep an eye on the fine print regarding prepayment penalties. High earners often find themselves with extra liquidity and may want to pay off a loan early to save on interest. If your lender charges a fee for doing this, you might find that the “cheap” loan becomes quite expensive in the end. Before signing, ask explicitly: “Is there a penalty for paying this loan off in full within the first twelve months?” For a high-income individual with fluctuating cash inflows, this flexibility is a non-negotiable requirement for a smart lending partner.