The 7 Best Lenders for a Personal Loan with a Co-signer in 2026
Last updated: 2026-10-17
Trying to find a lender when your credit score is lagging can feel like driving through a thick fog without headlights. Many people find themselves turning to a parent or a close friend to co-sign, hoping that someone else’s good credit can bridge the gap. This simple favor often makes the difference between a rejected application and getting the cash needed for an urgent car repair or a medical bill.
When you weigh your options, don’t just look at the monthly payment. You have to look at the big picture, including how fast you can get the cash and what the total cost will be over the years. A low monthly payment sounds great until you realize the loan term stretches to 72 months, making the interest payments skyrocket. Similarly, a lender that promises lightning-fast funding might hide massive origination fees that make the loan much more expensive than a traditional bank.
- FastLendGo
- OneMain Financial
- Upgrade
- Together Loans
- U.S. Bank
- MoneyLion
- MedLoan Finance
How the Top Lenders Were Evaluated
We spent a significant amount of time looking at current market offerings specifically for people using a co-signer. We wanted to see how lenders handle an application when two different people are involved. It was important to know if the requirements for the co-signer were clear or if the fine print was buried under layers of confusing language.
We investigated whether companies required a joint application or if they allowed a co-signer to simply act as a guarantor. This distinction matters because it changes how much of a risk the second person is taking on. We focused on lenders that made the process straightforward rather than those that added unnecessary paperwork to the pile.
Transparency was our main priority. We looked for companies that provided quick decisions, clear interest rates, and various loan amounts. We also checked the “friction” of the application process. This meant looking at how many documents you need to upload, how easy it is to sign things digitally, and how clearly they explain the Annual Percentage Rate (APR).
| Lender Name | Loan Amounts | Key Terms/Rates | Funding Speed | Credit Focus |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | see site | see site | Bad to Great Credit |
| OneMain Financial | $1,500 – $30,000 | Rates from 11.99% APR | As soon as 1 hour | Bad Credit Friendly |
| Upgrade | Up to $50,000 | Fixed rates available | Fast funding | Credit Health focus |
| Together Loans | Up to $10,000 | 24 – 60 months | 24-hour approval | Trust-based/Bad Credit |
| U.S. Bank | see site | see site | see site | Traditional Banking |
| MoneyLion | Up to $100,000 | see site | Fast/Expedited available | Credit Building focus |
| MedLoan Finance | $500 – $100,000 | 12-18 Months Interest Free | see site | Medical Specific |
Top-Rated Co-signer Loan Options for 2026
1. FastLendGo
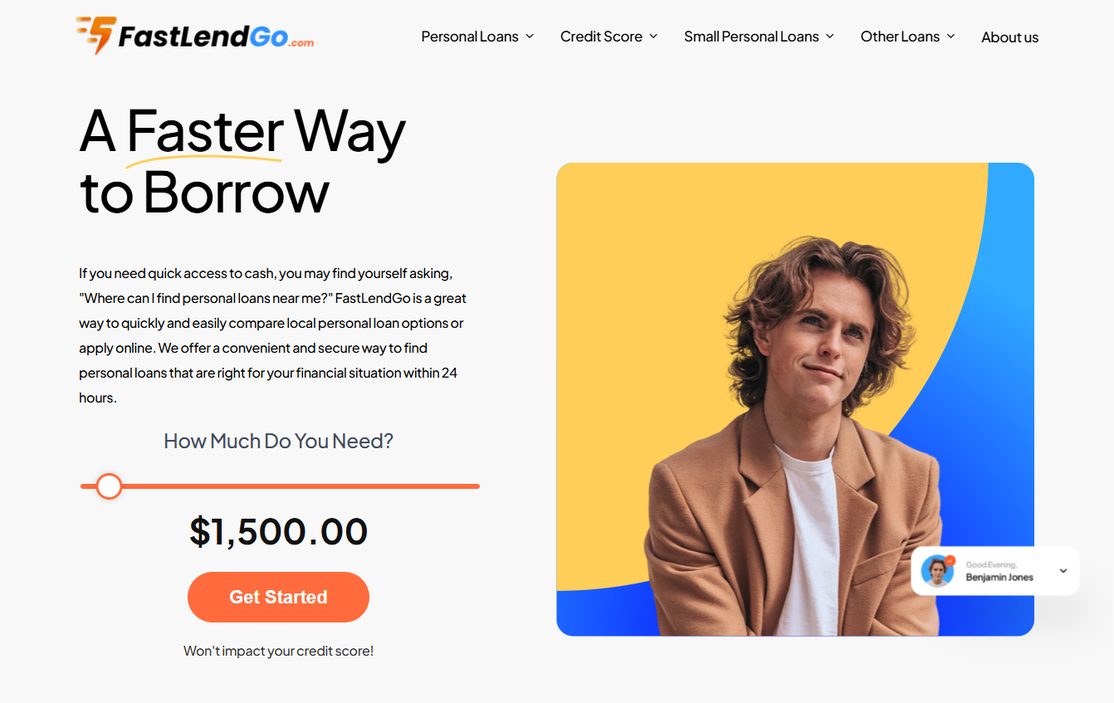
FastLendGo helps people who need cash quickly without jumping through a dozen hoops. They work with all sorts of people, from someone needing a $500 emergency fix to someone looking for a larger loan for a major life change. Their rules aren’t as stiff as a bank’s mortgage department, which makes them a good fit for gig workers or anyone with a fluctuating paycheck. (fastlendgo.com)
This lender is a lifesaver if you have a “thin” credit file. If you haven’t used much credit in the past, standard computer algorithms might struggle to understand your reliability. They offer specialized options for high earners and those with poor credit, ensuring almost anyone can find a way to borrow. It is a helpful way to use a co-signer to show the stability that your own history might not prove yet.
Pros:
- Loan amounts start at $500, making them great for small emergencies.
- They cover things like dental work or car repairs so you don’t need multiple loans.
- Flexible options exist for many different credit levels.
Cons:
- They focus on specific needs, so they might not be the best choice for general debt consolidation.
2. OneMain Financial
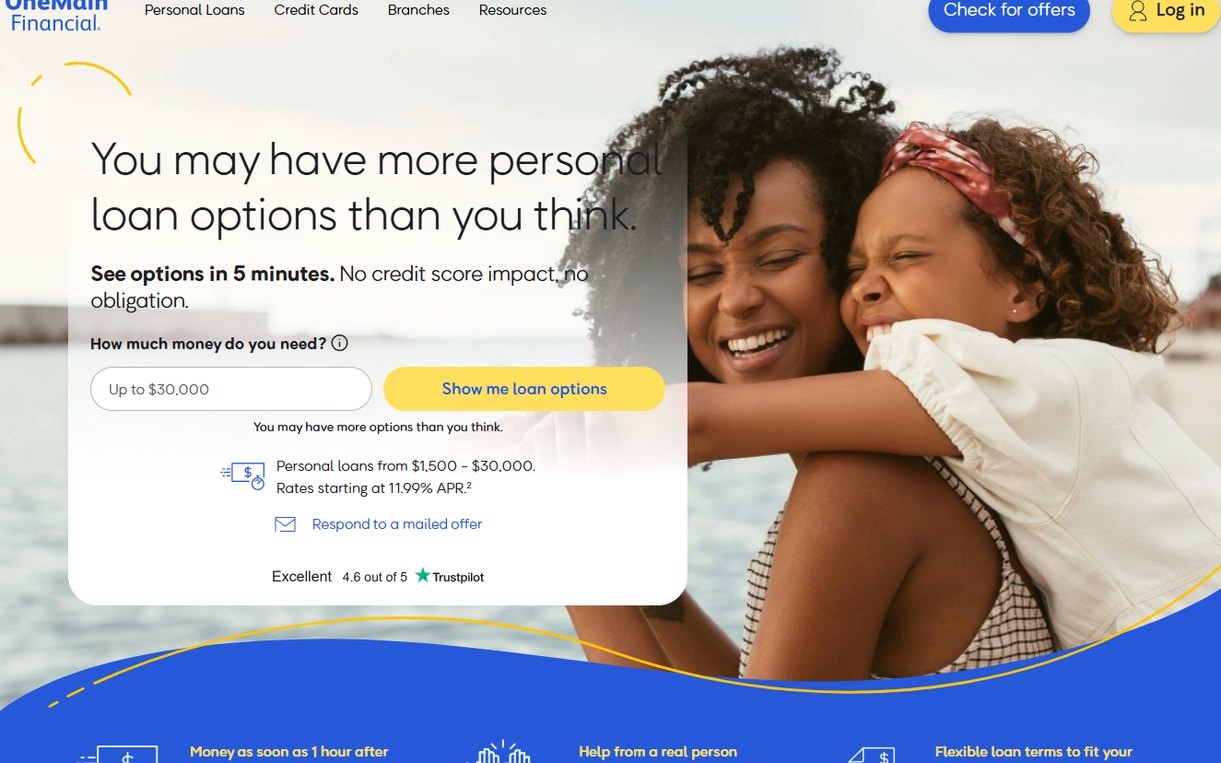
OneMain Financial is perfect for anyone who wants to talk to a real person instead of just an app. With over 1,300 physical branches, they have a presence that most online lenders simply can’t match. If you feel uncomfortable explaining your finances to a computer, sitting down with a loan officer in a real office can make you feel much more secure.
They are built for speed. In some cases, you can have your money just one hour after you sign the paperwork. Their joint loan options are also very easy to use, which helps couples or family members share the responsibility. It takes the guesswork out of having a co-signer on the line.
Pros:
- You can get funding incredibly fast, sometimes within an hour.
- A huge branch network means you can get in-person help whenever you need it.
- Joint loans for $1,500 to $30,000 make the co-signer setup very simple.
Cons:
- If your credit is low, the interest rates can get quite high, adding up over time.
3. Upgrade
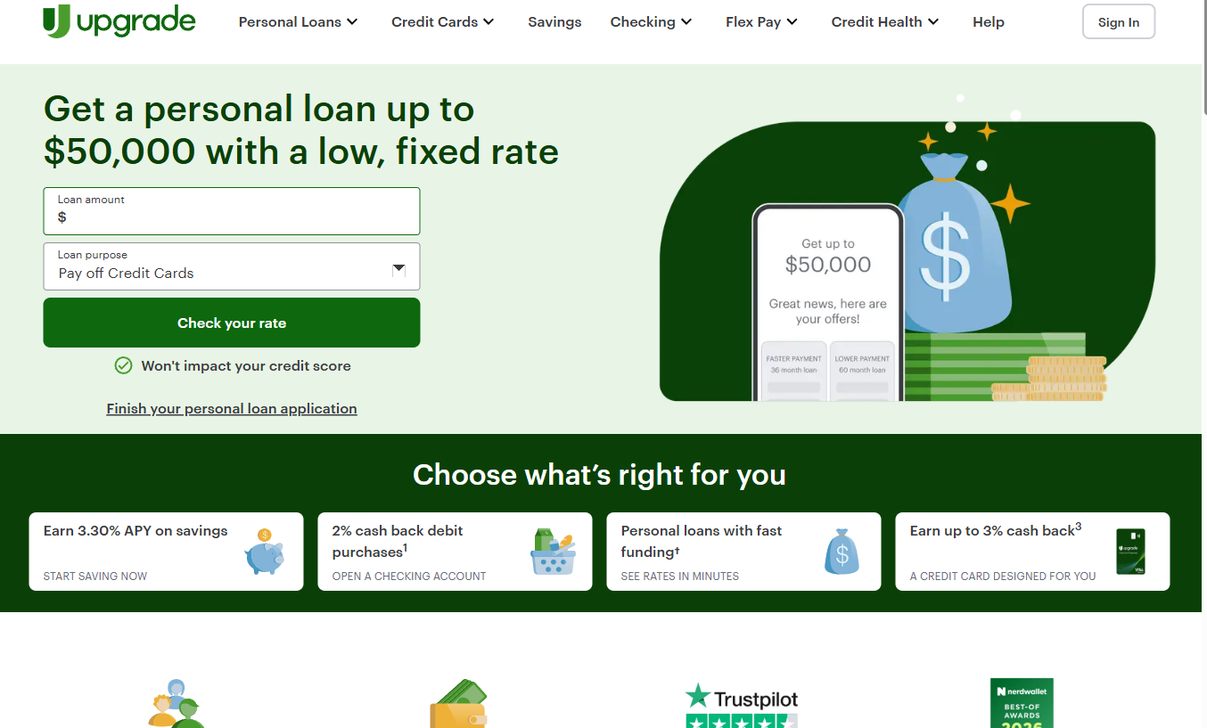
Upgrade takes a very modern approach, focusing on your financial health over the long haul. They offer everything from credit cards to savings accounts, which makes them a one-stop shop for your wallet. Their website is easy to use, and you can play around with different repayment numbers before you sign anything.
If you are trying to consolidate debt or pay for a big purchase, Upgrade makes the application very smooth. One of the best things they offer is a “soft pull” credit check. This means you can see your estimated monthly payment and APR without hurting your credit score, which is great for shopping around.
Pros:
- Checking your rate won’t hurt your credit score.
- You can use the money for almost anything, like home repairs or debt.
- Some products even include cash back rewards.
Cons:
- The variety of their products might feel like a bit much if you just want one simple loan.
4. Together Loans
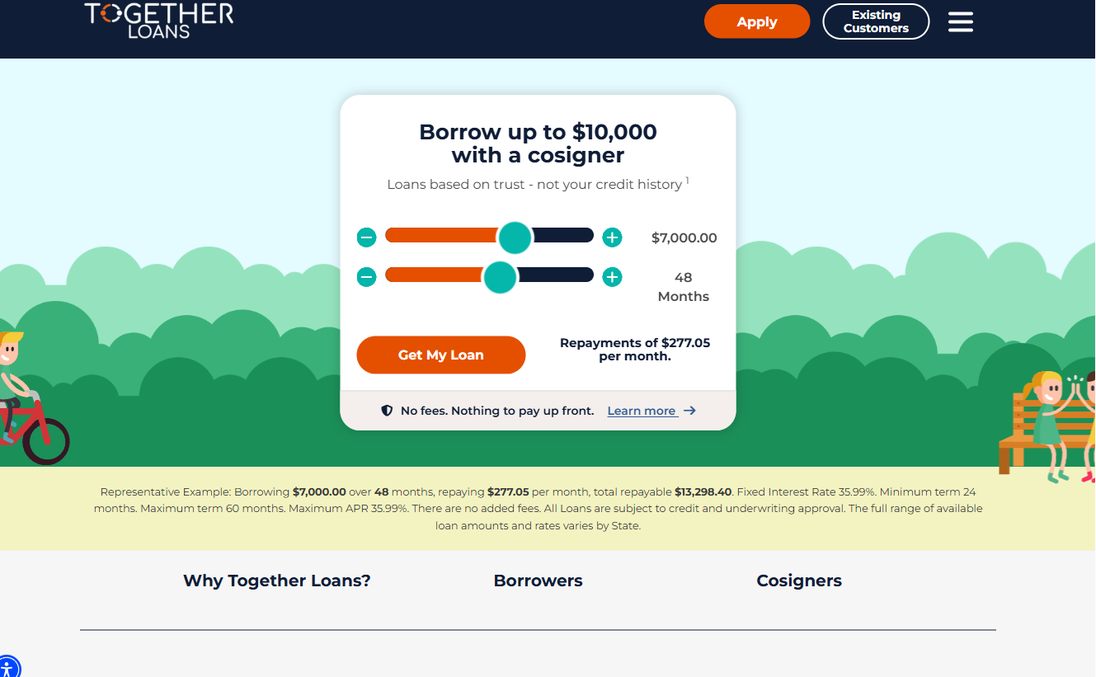
Together Loans does things a little differently by looking at trust rather than just a digital score. This is a huge advantage for people who have a great co-signer but a messy credit history. Life happens, and sometimes a single medical bill or a period of unemployment can tank your score, but these lenders look at the human side of the story.
They specialize in loans up to $10,000 and are incredibly fast, often giving approvals within 24 hours. If you need to pay an unexpected bill right away, this is a solid option. Using a co-signer here can help you get much better terms than you would ever find on your own.
Pros:
- They prioritize trust and personal circumstances over rigid algorithms.
- The 24-hour approval is perfect for urgent situations.
- There are no upfront fees, so you get the full amount you asked for.
Cons:
- The interest rates can be on the higher side, so check the fine print.
5. U.S. Bank
If you prefer the feeling of a massive, established institution, U.S. Bank is a very steady choice. They are a great option if you already bank with them. Having an existing account can make the verification process move a lot faster since they already know your cash flow.
They might not be as fast as a new fintech startup, but they have a massive infrastructure behind them. They offer everything from basic checking to wealth management. If you are planning a major life event like a wedding, the stability of a big bank can give you a sense of security.
Pros:
- They offer high levels of consumer protection and stability.
- You can get almost every financial service you need in one place.
- It is very easy to manage if you already use their banking services.
Cons:
- Their requirements for personal loans can be stricter than smaller, niche lenders.
6. MoneyLion
MoneyLion is built for people who do everything on their smartphones. Their app is designed to help you manage daily spending while also working to build your credit. It feels more like a financial assistant than just a place to get a loan.
They offer large loans up to $100,000, which is enough for major changes like starting school. Because they focus so much on credit building, they are a great partner for anyone trying to move away from needing a co-signer. Eventually, the goal is to stand on your own two feet without help.
Pros:
- They offer very high loan limits for large projects.
- The app includes many tools to help you learn about credit.
- The mobile interface is very easy to navigate.
Cons:
- Some of the faster cash features might come with extra fees.
7. MedLoan Finance
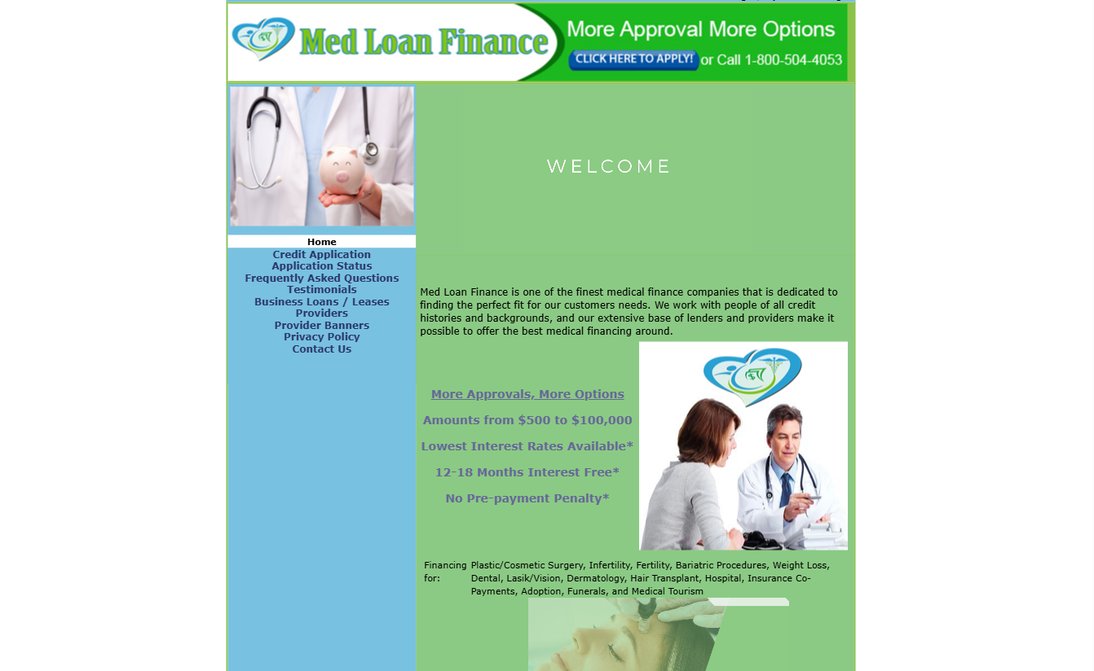
MedLoan Finance is built for one specific thing: medical bills. If you are paying for dental work, LASIK, or a surgery, they provide funding that is designed for the healthcare world. General personal loans don’t always understand the timing of medical costs, but these lenders do.
They offer various loan amounts and even have some interest-free options for certain timeframes. If you have a surgery coming up, using a specialist like this can be much cheaper than taking out a high-interest personal loan from a general lender.
Pros:
- They are specialists for dental and elective medical procedures.
- Interest-free options for 12-18 months can save you a lot of money.
- They handle large medical costs up to $100,000.
Cons:
- You can’t use this money for anything other than medical expenses.
Understanding the Risks for Co-signers
Being a co-signer is a huge deal. When a friend or family member signs that paper, they aren’t just saying you are a good person. They are legally agreeing to pay the debt if you don’t. If you miss a payment, the lender can go after them for the full amount, including interest and late fees. This can lead to lawsuits or even wage garnishment, and it can absolutely wreck their credit score.
The debt also shows up on their credit report. Even if you pay everything on time, the sheer amount of that loan might make it harder for them to get a mortgage or a car loan later. Lenders see that debt as a potential obligation that might prevent them from paying their own bills. It’s a heavy burden to place on someone you care about.
How to Prepare for a Co-signer Application
If you want the best chance of getting approved, you need to be prepared. This means more than just having your ID ready; you need a rock-solid plan for how you will pay the money back. We suggest taking these steps before you even start the application:
- Make a Payment Plan: Map out exactly when and how you will pay. Leave some extra room in your budget for months when things might get tight.
- Check the Co-signer’s Credit: Most lenders want your co-signer to have a score between 670 and 700. If their score is low, you might be wasting your time.
- Get Your Papers Ready: Lenders will want to see pay stubs, W-2s, and proof of where you live. Having these in a folder can save you days of waiting.
- Read the Contract Together: Don’t just sign the papers. Sit down with your co-signer and read the part about what happens if you miss a payment.
Navigating the Co-signer Process
Before you ask anyone to co-sign, you need to have a very honest conversation. They need to know that they are legally responsible for the money. If you have a falling out or if you lose your job, their credit score will take the hit just as much as yours. Money has a way of straining even the strongest family ties.
Don’t assume a co-signer is just a formality. Lenders treat them as a primary guarantor. If your co-signer’s credit isn’t much better than yours, the lender might still say no or give you a much higher interest rate. In that case, the co-signer isn’t actually helping you save money.
Finally, don’t borrow more than you actually need just because you can. Interest adds up fast, and the total cost can become a massive number over time. Use a co-signer to get a better deal, not just to borrow more money than you can handle.