Top 5 Lenders for Bad Credit Loans in New York: 2026 Rankings
Last updated: 2026-10-17
Managing money in New York City often feels like trying to walk through a sudden blizzard in Times Square. If your credit score isn’t where you want it to be, finding a lender that won’t simply turn you away can feel nearly impossible. Between the high cost of living in the five boroughs and the sudden arrival of emergency repairs or medical bills, New Yorkers frequently need liquid capital on short notice.
This guide is built for New Yorkers facing unexpected expenses who need reliable options without falling into the predatory traps often found in high-street storefront lenders. You shouldn’t have to choose between paying rent and falling victim to a debt trap. Finding the right balance between speed and cost is the secret to staying afloat in a high-pressure urban environment.
Selecting the right lender requires more than just looking at a single interest rate. You have to weigh the speed of funding against the long-term cost of the debt. A low interest rate is useless if the loan takes two weeks to process and your landlord requires payment tomorrow. Conversely, a lightning-fast loan might come with astronomical APRs that make repayment impossible.
We look at how these providers handle credit checks, how quickly they move money into your bank account, and whether their terms are transparent or full of hidden traps. We evaluate these factors based on real-world utility for someone living in a high-pressure city. Our goal is to help you see past the marketing and find actual financial utility.
- SkyOne
- United Finance
- JetzLoan
- Experian
- GreendayOnline
How These New York Loan Options Were Evaluated
The evaluation process focused on accessibility for individuals with less-than-perfect credit scores. We looked at whether a lender performs a hard credit pull during the initial inquiry phase. This matters because a hard pull can impact your score before you even know if you are approved. In a competitive market like New York, where credit utilization and score fluctuations are closely watched, a “soft pull” for quotes is a vital safeguard.
Speed of funding is also a massive factor for those in urgent situations. Whether it is a car repair needed to get to work or a sudden utility shut-off notice, time is of the essence. We prioritized lenders that move quickly without sacrificing the transparency of their terms. We wanted to see who actually gets money into your account when you need it most.
We also scrutinized the range of loan amounts available to ensure a variety of needs are met. A $500 loan might fix a broken appliance, but a $25,000 loan might be necessary to consolidate high-interest credit card debt that is stifling your monthly cash flow. We prioritized clarity regarding repayment terms to ensure the lenders listed provide a genuine service rather than a debt trap.
We specifically looked for indicators of “predatory lending,” such as excessive origination fees that are tacked onto the principal. We also checked for a lack of clarity regarding the total cost of credit over the life of the loan. If a lender hides the real cost behind fine print, they didn’t make our list.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirement |
|---|---|---|---|
| SkyOne | $500 – $50,000 | see site | Personal Loans available |
| United Finance | see site | see site | Installment loans available |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Experian | $2,000 – $50,000 | Same-day funding available | see site |
| GreendayOnline | $100 – $5,000 | As soon as the same day | Bad credit welcome |
The Definitive Ranking of Lenders
1. SkyOne
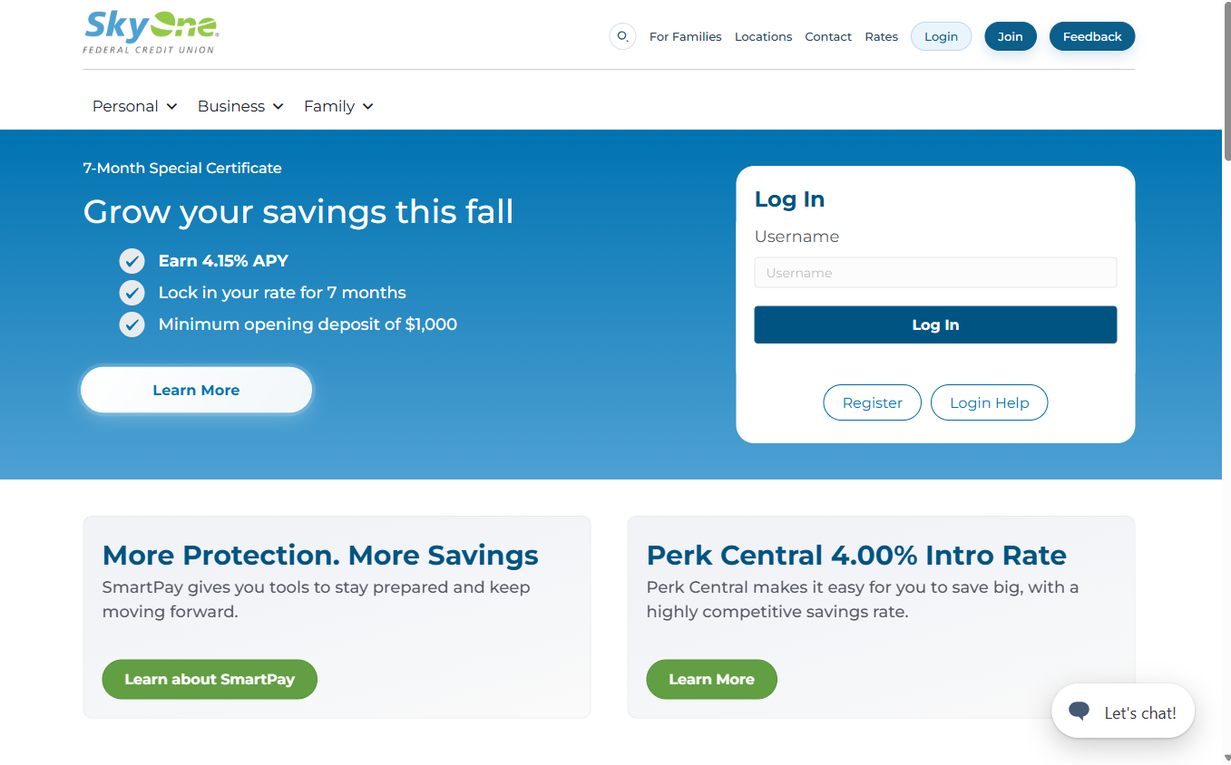
SkyOne operates as a federal credit union, offering a structured approach to personal financing. Unlike traditional commercial banks that may have rigid, automated rejection algorithms, credit unions are member-owned. This often makes them much more holistic in their approach to lending. They provide personal loans and lines of credit that might be a lifeline for those looking to stabilize their finances.
Their rates for personal loans can start as low as 13.99% APR. This is quite competitive when compared to the average interest rate of a high-interest credit card. If you are looking to manage a significant amount of debt or fund a major purchase—such as a down payment for a vehicle or a home renovation—their higher limits up to $50,000 provide significant breathing room for your budget.
This option is particularly suited for those who prefer a community-focused institution over a massive, impersonal bank. Because they are a credit union, the relationship is often more collaborative. This makes them a strong choice for those looking for long-term financial stability rather than a quick fix.
Pros:
- Competitive APR starting at 13.99% for personal loans.
- High maximum loan amounts up to $50,000.
- Offers both loans and lines of credit for flexibility.
Cons:
- Credit union membership requirements may apply.
2. United Finance
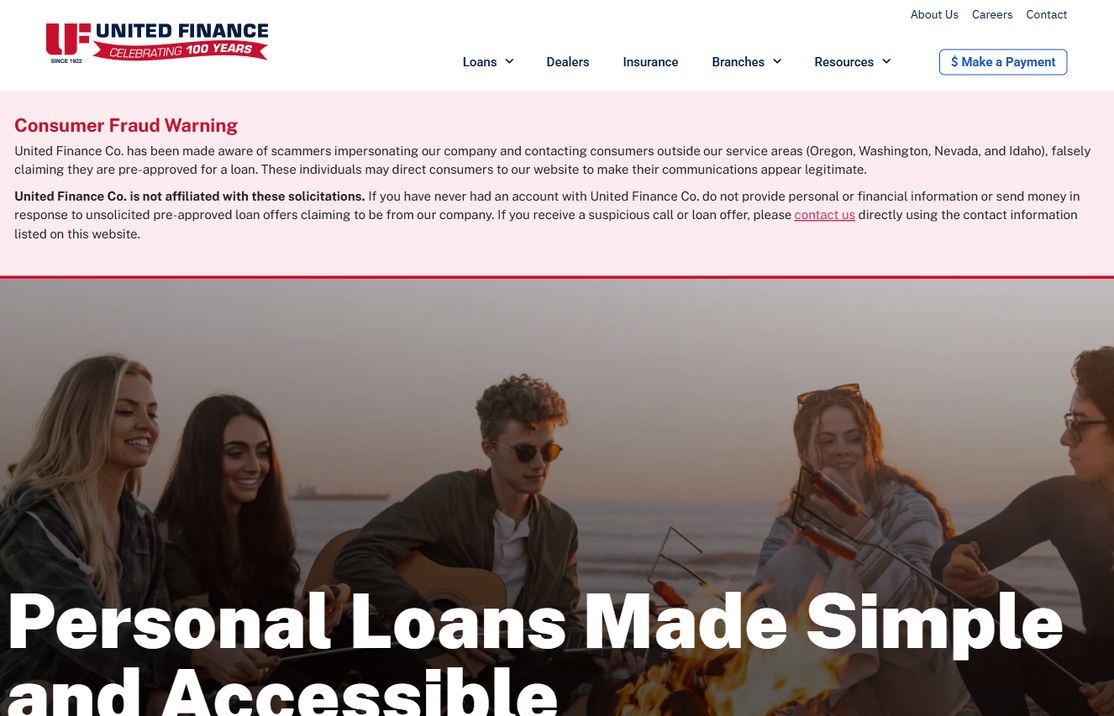
United Finance has been a staple in the lending industry since 1922, bringing decades of experience to the table. They focus on installment loans, which offer a more predictable way to manage repayments compared to high-interest payday loans. In an installment loan, you pay back a fixed amount of principal and interest over a set period. This allows for much tighter budgeting.
This is a stark contrast to “revolving” debt or payday loans where the interest can compound so rapidly that the principal remains untouched for months. They emphasize ethical lending and have issued warnings about scammers impersonating their brand. This dedication to security is vital for New Yorkers who are often targets of predatory financial solicitations via email or text.
When a lender has a history spanning a century, they have weathered multiple economic cycles. This gives them a level of institutional stability that newer, fintech-only startups may lack. It is a solid choice for those seeking a traditional, established lending experience with predictable monthly obligations.
Pros:
- Extensive history and established reputation since 1922.
- Focuses on installment loans rather than risky payday cycles.
- Strong emphasis on consumer fraud protection and security.
Cons:
- Service area is limited to specific states like Oregon and Nevada.
3. JetzLoan
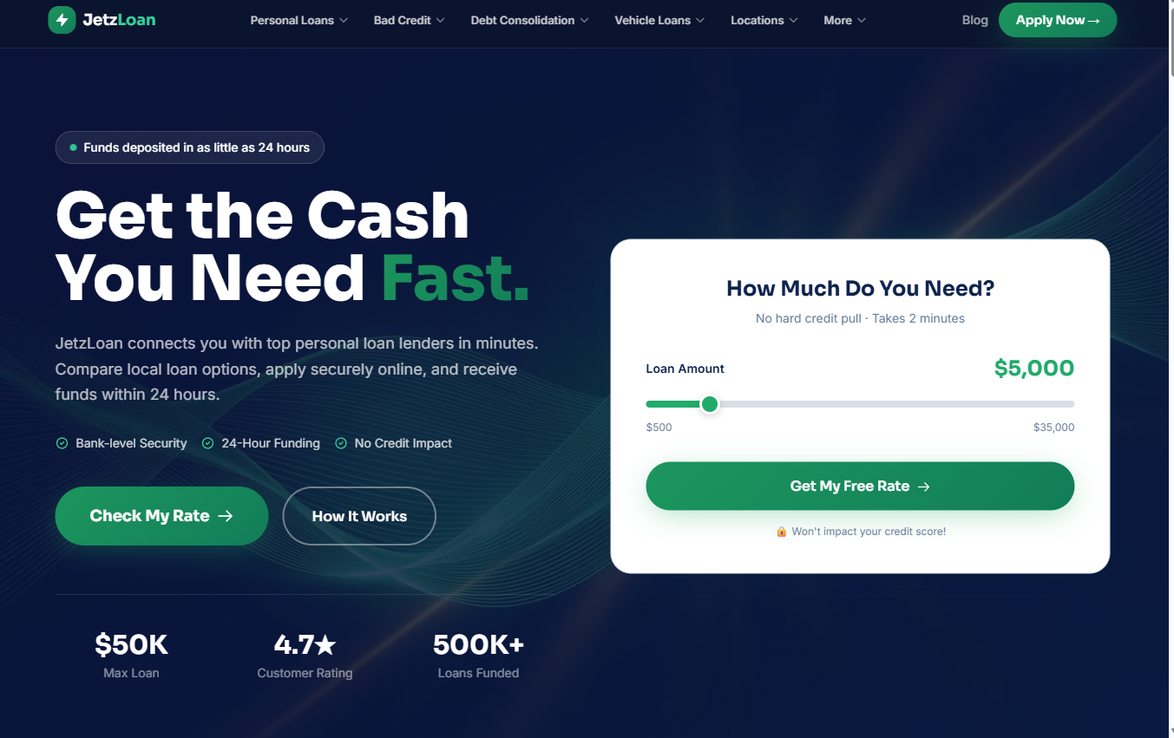
If you find yourself in a pinch and need cash yesterday, JetzLoan is built for speed. They specialize in connecting users with top lenders in just minutes. The most significant advantage here is the ability to check your rate without a hard credit pull. Your score stays safe during the comparison process.
This “pre-qualification” phase is essential. Many people mistakenly believe that applying for a loan is a guarantee of a score drop. With JetzLoan, you can shop around for the best terms without any immediate impact on your credit report. The platform is streamlined to be incredibly user-friendly, taking less than two minutes to fill out the initial form.
You won’t find the endless paperwork of a brick-and-mortar bank here. The digital interface is designed for someone on the go, perhaps using a smartphone while commuting on the subway. With funds potentially hitting your account in as little as 24 hours, it is a go-to for those who cannot afford to wait for traditional bank processing times.
Pros:
- No hard credit pull during the initial rate check.
- Extremely fast funding, often within 24 hours.
- User-friendly, quick two-minute application process.
Cons:
- Maximum loan amount is capped at $35,000.
4. Experian
Experian is a household name when it comes to credit monitoring, and their loan services reflect that expertise. They understand the intricacies of the credit scoring models better than almost anyone else. They offer personal loans ranging from $2,000 up to $50,000, with flexible repayment terms spanning 24 to 72 months. This flexibility is key when trying to balance monthly expenses.
A longer term means lower monthly payments, which can provide immediate relief to your monthly cash flow. However, keep in mind this will increase the total interest paid over the life of the loan. They are particularly useful for those looking to improve their financial standing through tools like credit boosting. By using services that report utility or rent payments, you might be able to raise your score.
This creates a virtuous cycle. You use the loan to fix a financial hurdle, and then use Experian’s ecosystem to ensure your score is higher when you go to refinance or buy a car in the future. It is a way to turn a temporary setback into a long-term advantage.
Pros:
- Same-day funding is available for certain loan types.
- Flexible repayment terms up to 72 months.
- Integrated tools to help boost credit scores.
Cons:
- Approval odds and score increases are not guaranteed.
5. GreendayOnline
GreendayOnline is designed for those who need small, quick injections of cash to cover immediate gaps. They offer installment loans ranging from $100 to $5,000. This is a niche service meant for emergency situations where the primary goal is speed and ease of access. Think of it as a “micro-loan” option for life’s small, sudden inconveniences.
While it won’t help you consolidate a massive mountain of debt, it is excellent for bridging the gap between paychecks. The process is entirely online, making it incredibly convenient for busy New Yorkers on the move. They specifically welcome those with bad credit, providing a path to cash that doesn’t require a grueling, traditional application process.
This makes them an essential fallback for individuals who have been stung by previous credit setbacks but need to move forward immediately. It is a simple, straightforward solution for those who just need a little extra help to get through the month.
Pros:
- Extremely low minimum entry point starting at $100.
- Very fast approval and same-day cash availability.
- Designed specifically to accommodate bad credit applicants.
Cons:
- Loan amounts are relatively small compared to other lenders.
How to Compare Loan Offers: A Step-by-Step Guide
When you have multiple offers on the table, the numbers can become a blur of percentages and dates. To make an informed decision, follow this systematic approach:
- Calculate the APR, not just the Interest Rate: The interest rate is the cost of borrowing the principal, but the Annual Percentage Rate (APR) includes fees like origination fees or processing costs. Always use the APR as your primary comparison metric.
- Determine Your “Maximum Monthly Outflow”: Before looking at the loan, look at your budget. If you can only afford an extra $150 a month, don’t take a loan that requires a $200 payment, even if the total interest rate is low.
- Check for Prepayment Penalties: Some lenders charge you a fee if you try to pay the loan off early. If you expect a tax refund or a bonus later this year, you want a loan that allows you to pay it off early without penalty.
- Verify the Funding Timeline: If you need the money for an emergency, ask specifically, “When will the funds be cleared and available in my bank account?” There is a difference between “approved” and “available.”
Common Pitfalls to Avoid in the NYC Lending Market
The sheer density of financial services in New York can be overwhelming, and predatory lenders often use high-pressure tactics to close deals. Be wary of any lender that calls you repeatedly or uses aggressive language like “last chance” or “immediate rejection if you don’t act now.” Legitimate lenders are professional and will allow you the time to read the fine print.
Another common mistake is “loan stacking.” This occurs when a borrower takes out a small, high-interest loan to pay off a different high-interest loan. While it might feel like you are solving a problem, you are actually just moving the debt around while the interest continues to accumulate. If you find yourself needing to take out a second loan to pay for the first, it is time to stop and seek debt counseling.
Finally, always verify the legitimacy of online lenders. Even if a website looks professional, ensure they are registered to operate in your state and have a clear physical address and verifiable customer reviews. In a digital world, a polished interface is the bare minimum; actual stability is proven through historical reputation and transparent terms.
Navigating Your Loan Options Wisely
Before signing any paperwork, take a moment to breathe. It is easy to get swept up in the excitement of a quick approval, but you must look closely at the total cost of borrowing. Always ask if there are origination fees or prepayment penalties that might make the loan more expensive than it looks on the surface. A $1,000 loan that costs $100 in fees just to receive the money is significantly more expensive than the advertised rate suggests.
Avoid the temptation to take out multiple small loans from different sources to cover one large debt. This can lead to a downward spiral that is very difficult to escape. Instead, try to consolidate your needs into one manageable monthly payment whenever possible to keep your budget predictable and your stress levels low. Managing one single, predictable payment is much easier for the human brain to process than juggling five different due dates and varying interest rates every month.